Catastrophic Injury Lawyers in Pennsylvania: Valuing a Lifetime
Brain and spinal injuries, amputation and severe burns, where the cost is measured in decades.
- 4.7 from 140 Google reviews
- PA bar admitted since 1982
- No fee unless we recover
- Answered 24 hours
A catastrophic injury claim is valued over a lifetime rather than to the end of treatment. That requires a life care plan and economic analysis, and it means finding every available insurance policy, because a single policy rarely covers decades of care.
Why these are valued differently
An ordinary injury claim adds up medical bills, lost wages and an amount for the harm. A catastrophic claim projects forward across a life: attendant care, equipment replacement cycles, home and vehicle modification, medication, therapy, surgical revisions, and lost earning capacity over a career that will not happen.
Settling before that projection exists is how families end up funding care themselves twenty years later. It is the single most costly mistake in this area.
The life care plan
A life care planner, working with the treating physicians, produces a costed schedule of future needs. An economist then reduces it to present value and calculates lost earning capacity.
It is expensive to produce and it is the backbone of the claim. Without it a defendant negotiates against your medical bills to date, which in a catastrophic case bear no relationship to the real cost.
Finding every policy
One policy rarely covers a catastrophic injury. The work is identifying all of them:
- The at-fault party’s liability coverage, and any umbrella policy above it.
- Commercial policies where a vehicle or premises was used for business.
- Your own underinsured motorist coverage, potentially stacked.
- Employer and contractor policies where the injury happened at work.
- Product manufacturers, where equipment contributed.
- Property owners and their insurers.
Preserving benefits
A large recovery paid directly to an injured person can disqualify them from Medicaid and other needs based benefits they will rely on for life. A special needs trust or similar structure can preserve eligibility while the funds are used for their benefit.
This has to be planned before settlement, not afterwards. It is one of the most consequential technical points in this area and it is regularly missed.
Structured settlements
Part of a recovery can be structured as guaranteed periodic payments rather than a lump sum, which addresses the risk of funds being exhausted early. Whether it suits a particular family depends on their circumstances, and it is worth considering properly rather than dismissing.
Do not rush
Defendants and their insurers know that families in these situations are under acute financial pressure. Early offers exploit that. The right time to value a catastrophic claim is when the medical picture has stabilised enough for a life care plan to mean something.
The attorneys who handle these cases
Every one of these bar numbers is searchable on the Pennsylvania Disciplinary Board register. The person who takes your call is the person at your hearing.
-
Kenneth R. Schuster
Founding Member
Read Kenneth’s background -
Justin M. Bernstein
Associate
Read Justin’s background -
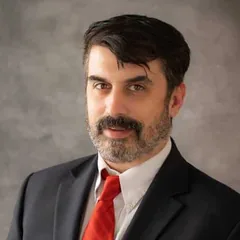
Christopher D. Gasda
Associate
Read Christopher’s background -
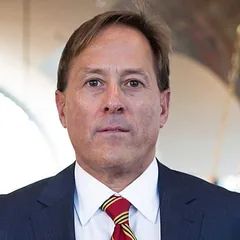
Anthony S. Pinnie
Of Counsel
Read Anthony’s background -
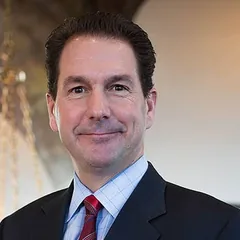
Joseph J. Jachetti
Associate
Read Joseph’s background -
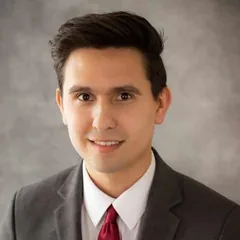
Andrew Valentin
Associate
Read Andrew’s background
Questions people ask us about this
How is a catastrophic injury claim valued?
Over a lifetime rather than to the end of treatment. A life care planner produces a costed schedule of future needs including attendant care, equipment replacement, home modification and surgical revisions, and an economist reduces it to present value alongside lost earning capacity.
Why should I not settle early?
Because the medical bills to date bear no relationship to the real cost. Settling before a life care plan exists is how families end up funding decades of care themselves. Insurers know the financial pressure families are under, and early offers reflect that rather than the claim's value.
The at-fault driver has minimal insurance.
One policy rarely covers a catastrophic injury, so the work is finding all of them: umbrella policies, commercial coverage where a vehicle or premises was used for business, your own stacked underinsured motorist coverage, employer and contractor policies, and product manufacturers.
Will a settlement affect Medicaid or other benefits?
It can disqualify an injured person from needs based benefits they will depend on for life. A special needs trust or similar structure can preserve eligibility while the funds are used for their benefit, but it has to be planned before settlement rather than afterwards.
Should we take a lump sum or structured payments?
Part of a recovery can be structured as guaranteed periodic payments, which addresses the risk of funds being exhausted early. Whether it suits a family depends on their circumstances, and it deserves proper consideration rather than being dismissed as inflexible.
Both Delaware County offices
Walk in, or call. Both are answered 24 hours.
Media Head office
334 W Front StMedia, PA 19063
Open 24 hours
4.7 from 135 Google reviews
Serving central, north and west Delaware County.
Chester Satellite
405 Avenue of the StatesChester, PA 19013
Open 24 hours
5.0 from 5 Google reviews
Serving south and riverfront Delaware County.
Tell us what happened
Two questions to start. No contact details until the second step, and nothing you send here commits you to hiring us.
- You pay nothing unless we recover for you
- A named attorney reads every case review
- Both offices answer 24 hours, so you can call instead
Would rather talk now? (610) 601-2980